Read this new article on the global car industry on the economist. My take in terms of impact on the indian industry
- The weaking of the global companies like GM, Ford and their suppliers like Delphi etc would be a great positive for the indian auto parts industry as these companies would have to look at further cutting costs to survive. Indian auto part companies are very cost competitive and are rapidly moving up the value chain
- Critical factor for indian auto parts companies would be how rapidly they can scale up and meet the global quality and service standards ( provided they get some support on infrastrucutre ). Also they can avoid cost pressures if they develop the required technology and IP.
- Not been able to come to conclusion on it would impact the domestic car industry...will it be beneficial for maruti, Tata motors etc ??
Wednesday, September 14, 2005

Is the market overvalued ?
I have been reading a lot of analysis on the market valuation levels. A few articles are citing that at a PE of 14 - 15 the market is not too overvalued and should give good returns.
On the other hand , some statistics show that market is fairly or overvalued as the ROE for the indian industry is at its peak, Interest rates low, inflation low and the demand robust. As a result we are seeing these PE levels which are at the peak of a cycle and the normalised PE should be close to 17-18.
I find both arguments plausible, but my money is on the overvaluation side. I have become fairly cautious for some time and would be looking at initiating selling if the markets keep rising.
Also the overall market valuations are important if one is invested in index funds or ETF's. Otherwise rather than concentrating on the market, i am looking at my individual holdings and would start reducing them if they start getting more overvalued (i think some are fairly close to their overvaluation levels)
Although i am not invested in commodity companies, i would look at their valuation levels more closely and would even look at selling them as my thought process is that commodity cycle is at a peak and industry profits are at a cyclical peak (for steel, cement etc ) due to robust demand, high capacity utilisation, low debt and interest level. PE for these companies is very low and i would not base my evaluation on those PE as the earnings are at a cyclical peak. In addition a lot of capacity addition is starting now, for ex: Tata steel seems to have announced a huge capex plan. So i would be wary of putting any money or holding onto commodity companies
Any thoughts ? please share with me
A New Blog
I have added a new blog by Prof Sanjay bakshi . Should be interesting to read his comments / articles and analysis
A New Blog
I have added a new blog by Prof Sanjay bakshi . Should be interesting to read his comments / articles and analysis
Saturday, September 10, 2005
Business model of Ratings agency - Crisil
I am looking at the financial numbers of crisil. My thinking was that CRISIL and any other rating agency would have a good business model. On looking at the numbers i have been completely blown away.
- Return on networth - 20 % +
- Return on capital employed in business - 80 % (approximate ). The company has about Rs100/share of investment
- Net profit is almost equal to cash flow as a rating agency would not have too much fixed expenses (other than offices which can be bought or leased)
- Not much of working capital requirement (close to zero)
- Net margins of 20% +
- Strong competitive advantage in the form of a strong brand name ( CRISIL or ICRA etc ). Any company wanting to get rated will have to go to these companies ...sometimes to all of them ( and i cant think of new companies being able to get into this business easily)
- additional lines of business through these relationships with companies like advisory services, research services etc which provides additional revenue streams.
So if everything is so good , why not buy the stock ...?? looked at the price and ofcourse the market is smart enough to recognise a good business. The stock sells at a PE of around 35. So it seems to be a great business available at not a great price. I will give it a pass ..but will continue studying the business model
Business model of Ratings agency - Crisil
I am looking at the financial numbers of crisil. My thinking was that CRISIL and any other rating agency would have a good business model. On looking at the numbers i have been completely blown away.
- Return on networth - 20 % +
- Return on capital employed in business - 80 % (approximate ). The company has about Rs100/share of investment
- Net profit is almost equal to cash flow as a rating agency would not have too much fixed expenses (other than offices which can be bought or leased)
- Not much of working capital requirement (close to zero)
- Net margins of 20% +
- Strong competitive advantage in the form of a strong brand name ( CRISIL or ICRA etc ). Any company wanting to get rated will have to go to these companies ...sometimes to all of them ( and i cant think of new companies being able to get into this business easily)
- additional lines of business through these relationships with companies like advisory services, research services etc which provides additional revenue streams.
So if everything is so good , why not buy the stock ...?? looked at the price and ofcourse the market is smart enough to recognise a good business. The stock sells at a PE of around 35. So it seems to be a great business available at not a great price. I will give it a pass ..but will continue studying the business model
Friday, September 09, 2005
Impact of High petrol prices
Have been thinking of how higher petrol prices would affect indian industry. My opinion is that companies like FMCG / IT services / Telecom should not effected much , either due to their inherent pricing ability or because fuel costs are low for them and affect them only indirectly.
The above event should impact oil companies postively ( hopefully they will not go bankrupt). Commodity businesses may get impacted badly if the demand falters and the costs go up. Metals/ Cement / Steel etc could get impacted negatively.
Cant think of the impact on retail / Media and other such industries. They would have some second or third order impact ( less disposable income leading to lower demand ? ) ...
I think the bigger impact could be on inflation and interest rates. I would stay away from fixed income funds for some time atleast. Also individuals with variable rate loans could be impacted. Will it impact the housing market ...not really sure about it
Pricing strenght - A key indicator of competitive advantage
I was reading an interview of warren buffett a few days back. He was asked on what kind of businesses he prefers. His replied the ones where he can increase the price of the product ahead of inflation (he gave the example of see's candies ). He also noted that one should avoid businesses where one has to pray before increasing the price by one cent (he gave the example of berskhire hathway - the textile company where they found it diffcult to increase prices )
The above comment got me thinking. Pricing strength of a business is a very powerful indicator of competitive advantage enjoyed by the business. Think of FMCG companies like HLL, P&G, marico . These companies have been able to increase their prices (although that ability has come down in recent past due to higher competition ). On the other end companies like steel , cement typically can increase prices only when there is supply shortage (which is only for a limited period of time)
I have found the above way of looking at a business a very powerful tool of checking if a business has enduring competitive advantage.
How about telecom companies or IT services companies ...their pricing ability does throws up interesting insights ..although i have not been able to come to a conclusion
Wednesday, September 07, 2005
How VOIP would impact the Telecom industry
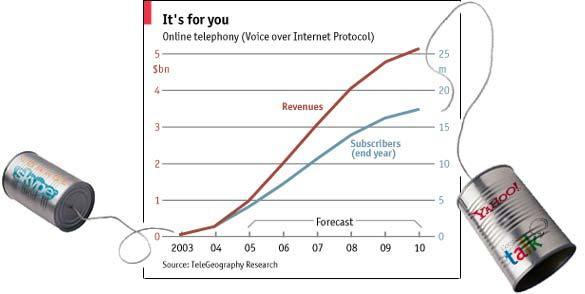
Read this article on how VOIP is impacting the telecom companies (or could impact). The article focuses on the number of users switching to VOIP and that the traditional companies could see a fall of upto 25 % revenue in the next few years.
I think VOIP could be the disruptive technology often referred to by Clayton M. Christensen in his book 'the innovator's dilemma' . This technology although just below the required performance levels of the regular telecom market is fast improving and moving into the rapid adoption phase. Now with microsoft, skype and google behind it , it should not be long before more rapid adoption happens.
all of the above should be great for the consumer, but what will happen to the telecom industry ...i would guess that their entire business model could get disrupted in the next few years ...what does this mean for companies like VSNL, bharti or reliance infocomm ?
some of them could face pain but would evolve with the new technology like reliance or bharti ..but i would not be too optimisitic for VSNL, MTNL and some others
i would be wary of investing in the telecom sector for a long term basis
How VOIP would impact the Telecom industry
Read this article on how VOIP is impacting the telecom companies (or could impact). The article focuses on the number of users switching to VOIP and that the traditional companies could see a fall of upto 25 % revenue in the next few years.
I think VOIP could be the disruptive technology often referred to by Clayton M. Christensen in his book 'the innovator's dilemma' . This technology although just below the required performance levels of the regular telecom market is fast improving and moving into the rapid adoption phase. Now with microsoft, skype and google behind it , it should not be long before more rapid adoption happens.
all of the above should be great for the consumer, but what will happen to the telecom industry ...i would guess that their entire business model could get disrupted in the next few years ...what does this mean for companies like VSNL, bharti or reliance infocomm ?
some of them could face pain but would evolve with the new technology like reliance or bharti ..but i would not be too optimisitic for VSNL, MTNL and some others
i would be wary of investing in the telecom sector for a long term basis
Tuesday, September 06, 2005
Kothari products ltd - A Net cash graham situation
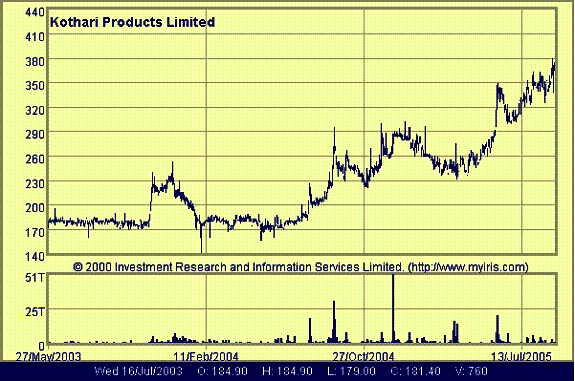
I was running my screen in the year 2003 and came across kothari products. This was a company with 240 crs cash and equivalent (net of debt) on the balance sheet with a market cap of 80 crs ( i think they had 40 mn outstanding shares @ 170 rs / share). They currently have almost 300 crs (around 600 rs per share )
They were fairly profitable (although the profits were down). The market had beaten down the price due to legislation issues (The maharashtra government had banned Pan masala / gutka - their main products). The company was still profitable, although the profits had come down due to drop in sales. Its free cash flow is same as its net profit because Gutka and other tobacco products require little capex for plant and machinery or working capital. The main asset is the brand (in this case pan parag ). So their profits were pure cash for the owners
I bought the share at an price of Rs 160 – 170 a share and sold around 260 per share. The reason I sold was lack of information from the company ( their website is poorly updated in terms of financial results). In addition, I was not sure what the promoters were planning to do with the cash ( the promoters hold almost 70 % of the company).
So what’s the point of the whole thing …Its not that it was a profitable investment. Rather, although I made money on the whole thing, I did not have a very comfortable feeling with the investment. If I compare it with the other purchases I have done such as asian paints, or a concor which are good businesses with good management, this one made me uncomfortable as there was no transparency from the company. In the end I decided to get out rather than face an unpleasant surprise from the management.
My investment philosophy is closer to that of buffet where I end up buying good to great companies at fair prices and get a good night’s sleep. The above was an experiment in a graham style investment. It was profitable and based on a sound approach. But somehow requires more diversification and purchase in not so great enterprises.
Do you have a similar experience? please feel free to share with me
Kothari products ltd - A Net cash graham situation
I was running my screen in the year 2003 and came across kothari products. This was a company with 240 crs cash and equivalent (net of debt) on the balance sheet with a market cap of 80 crs ( i think they had 40 mn outstanding shares @ 170 rs / share). They currently have almost 300 crs (around 600 rs per share )
They were fairly profitable (although the profits were down). The market had beaten down the price due to legislation issues (The maharashtra government had banned Pan masala / gutka - their main products). The company was still profitable, although the profits had come down due to drop in sales. Its free cash flow is same as its net profit because Gutka and other tobacco products require little capex for plant and machinery or working capital. The main asset is the brand (in this case pan parag ). So their profits were pure cash for the owners
I bought the share at an price of Rs 160 – 170 a share and sold around 260 per share. The reason I sold was lack of information from the company ( their website is poorly updated in terms of financial results). In addition, I was not sure what the promoters were planning to do with the cash ( the promoters hold almost 70 % of the company).
So what’s the point of the whole thing …Its not that it was a profitable investment. Rather, although I made money on the whole thing, I did not have a very comfortable feeling with the investment. If I compare it with the other purchases I have done such as asian paints, or a concor which are good businesses with good management, this one made me uncomfortable as there was no transparency from the company. In the end I decided to get out rather than face an unpleasant surprise from the management.
My investment philosophy is closer to that of buffet where I end up buying good to great companies at fair prices and get a good night’s sleep. The above was an experiment in a graham style investment. It was profitable and based on a sound approach. But somehow requires more diversification and purchase in not so great enterprises.
Do you have a similar experience? please feel free to share with me
Monday, September 05, 2005
A great talk on value investing from Prof. Bakshi
I visit prof. bakshi's blog regularly. He just posted a talk he gave on valueinvesting at the oxford bookstore in 2002. Great presenation with examples which have done well in the last 3 years. One can learn a lot on valueinvesting (and more in an indian context) from him and his posts.
Watchout investors !!
A new website from SEBI and ministry of company affairs which lists any non complaince or any voilation of guidelines or rules by people associated with any public listed companies. Great step towards transparency and investor eductation !!
watchoutinvestors.com is a national web-based registry covering entities including companies and intermediaries and, wherever available the persons associated with such entities, who have been indicted for an economic default and/or for non-compliance of laws/guidelines and/or who are no longer in the specified activity. This information which is presently disorganized, difficult-to-use and is spread across a large number of sources i.e. websites, databases, publications, notifications and orders of the government and of other organizations, agencies, courts of law, tribunals and commissions, has been aggregated, indexed, standardised ,reformatted and re-presented in a form and manner that can be accessed in a user friendly manner.
watchoutinvestors.com is a national web-based registry covering entities including companies and intermediaries and, wherever available the persons associated with such entities, who have been indicted for an economic default and/or for non-compliance of laws/guidelines and/or who are no longer in the specified activity. This information which is presently disorganized, difficult-to-use and is spread across a large number of sources i.e. websites, databases, publications, notifications and orders of the government and of other organizations, agencies, courts of law, tribunals and commissions, has been aggregated, indexed, standardised ,reformatted and re-presented in a form and manner that can be accessed in a user friendly manner.
Blogging for dollar - A new business model for individuals ?
Came across this blog from darren. He seems to have made 100000 usd via blogging in the last 1 year. Seems to be an interesting business model. Can this become a full time source of income ? i dont think so ( and darren suggests the same).
But i think blogs can be become a powerful tool for small time entreprenuers and a creative outlet for a lot of people. In addition a lot of companies can use blogs for internal and external communication (with customers ). Microsoft seems to be doing so.
We may see some companies use blogs in addition to their website to get closer to their customer (experience marketing ?)
It would interesting to see how this medium develop. But it would be safe to say a handful will achieve prominence ( the ones which will pass the tipping point ??) , whereas the rest would remain a labor of love (or pain if you are in it for the money only )
there is an interesting post i read on mark cuban's blog on a similar topic - podcasting
Saturday, September 03, 2005
Good articles on value investing
Mr Sanjay bakshi is a visiting professor at Management Development Institute, Gurgaon, India. He has a blog - http://www.fundoo_professor.blogspot.com/ and a website http://www.sanjbak.com/ .
He is also the CEO of Tactica Capital Management, an investment boutique. There some very good articles on his website which really worth reading
He is also the CEO of Tactica Capital Management, an investment boutique. There some very good articles on his website which really worth reading
Tuesday, August 23, 2005
Reading a book on Bill miller
I have been reading a book on bill miller from janet lowe
A few things which I learnt
- It is critical to develop a multi-disciplinary model to evaluate companies. This is getting more important as new companies would have more intangible assets than tangible ones and would depend on network effects / customer lock-in etc to create value (like e-bay). even old economy companies will have some component of new economy companies (think about the website of most retailers )
- Importance of understanding business models of these new economy companies and avoiding slotting them into incorrect categories. Bill miller gives an example of amazon.com which is looked at as a retailer and as a result the market has got it wrong several times. According to miller, business model of amazon is closer to dell than walmart (although amazon is using the same wallmart strategy , but online – keep the gross margins constant and pass the benefits to the consumer to build scale )
- The market typically makes an error in evaluating a new business model and is slow to recognize it (but eventually it does). So an investor like miller who has the foresight , can beat the market on these companies (examples given were for dell and amazon )
- Concepts such as network effects, customer lock-in and increasing returns have been discussed briefly in the book with some example.
- Some example of companies which have both new and old economy models
- The book brings out bill miller’s capability to think independently and stand against the crowd ( there is an incident narrated in the book , where it seems in the baron’s panel , one of member asked if bill was drunk when he bought amazon in 2001 – eventually bill was vindicated on his decision
One the most important points which I learnt from the book was to develop an open mind on the new concepts which are coming up and the way they are being used by value investors like bill miller. The growth v/s value tag seems to be immaterial for any company as long as one can assess the intrinsic value of a company and buy it at a discount. Although I may find it difficult to apply these concepts directly, I think these new concepts would help me analyzing and appreciating the new business models which are developing
If the market is falling ..why am i smiling ?
for the same reason, when the price of a computer, telecom charges, or any other stuff which i need to buy falls !!
It allows me to buy more of it ....
The above way of thinking is ofcourse not original ...kind of learnt it from warren buffett. But having internalised it, it makes a lot of sense
so every day when the market falls , i smile and hope that the stocks which i am wanting to buy and have not been able to, would be available soon at a good price
Wednesday, August 17, 2005
Is it worth investing in the Oil sector

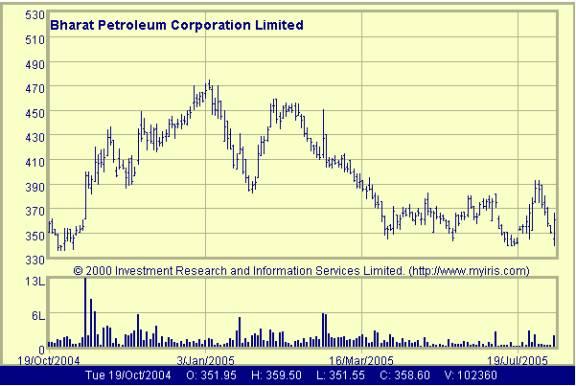
The goverment by controlling the prices is driving the sector to bankruptcy. Trying all kinds of permutations to keep the companies from going bankrupt (see article below). If the oil companies cannot charge market rate (shareholders subsidizing the customer ???!!) , then how is the sector going to make money.
I am still not able to get it (maybe i am missing something ). If the government ( the majority shareholder ) controls the pricing (and profit) of the oil companies at the expense of the minority shareholder with no concern other than the political impact, what is the value of these companies ? how does one value such companies where the future cash flow in addition to being dependent on a volatile oil market is also dependent on a whimsical majority shareholder which has a non economic agenda ! . This sector would start looking like indian railways if the oil prices remain high (which looks likely), that is chronically sick
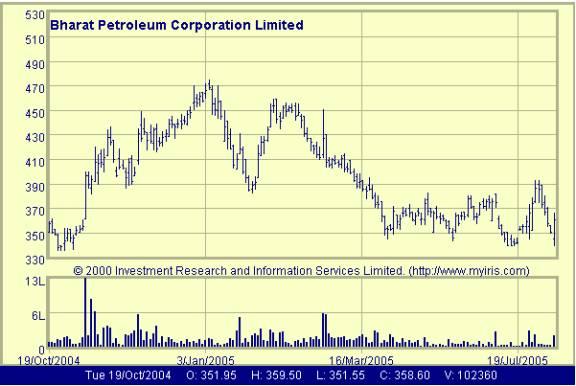
typically oil companies make good profits through forward contracts, hedging etc during rising oil prices (more so if they are vertically integrated). But the indian oil companies are actually down when the overall market is up ( see chart )
To provide cushion for under-recoveries — Standalone refineries may be merged with oil marketing cos --- From hindu business line
Our Bureau
New Delhi , Aug. 17
THE Ministry of Petroleum & Natural Gas is weighing the option of merging pure refining companies with oil marketing companies (OMCs) to enable the latter to cushion the impact of high global crude oil prices on their bottomline.
Due to the freeze by the Government on raising retail prices despite the rise in raw material cost, the fuel retailing business is seen as becoming economically unviable, resulting in OMCs such as Indian Oil Corporation, Bharat Petroleum Corporation, Hindustan Petroleum Corporation and IBP suffering losses.
However, standalone refiners in Chennai, Kochi and Mangalore are making profits as they get the international price for the fuel they produce.
Asked whether the Petroleum Ministry was contemplating such a move, the Petroleum Secretary, Mr S.C. Tripathi, told Business Line that, "various options are being considered. In view of the high crude oil price scenario, some serious structural changes could be made in the downstream sector."
About the suggestion made by the Committee on Synergy in Energy to oil companies asking them to consolidate their businesses, the Secretary said, "we are keeping that also in view."
Explaining the rationale behind such a consideration, a Petroleum Ministry official said standalone refiners were currently earning huge margins, while the OMCs were taking a hit. The merger could help in sharing refining margins with OMCs. "But this is a long-term view and may take some time," he said.
Meanwhile, the bleeding OMCs have been seeking a revision in the prices of the four petroleum products - kerosene, LPG, petrol and diesel.
The companies have incurred a cash loss of Rs 1,516 crore in July. They have sought Rs 5.29 per litre increase in petrol and Rs 4.54 a litre hike in diesel prices. Indications are that the Government is unlikely to consider the price revision before the end of the current session of Parliament.
Also, negotiations were on with the Finance Ministry to consider an excise duty cut, senior officials said.
The Government may consider a hike between Rs 1 and 2 per litre each combined with excise duty reduction on petrol from 8 per cent plus Rs 13 a litre to 8 per cent plus Rs 12 a litre and that on diesel from 8 per cent plus Rs 3.25 a litre to 8 per cent plus Rs 2.25 per litre.
Is it worth investing in the Oil sector
The goverment by controlling the prices is driving the sector to bankruptcy. Trying all kinds of permutations to keep the companies from going bankrupt (see article below). If the oil companies cannot charge market rate (shareholders subsidizing the customer ???!!) , then how is the sector going to make money.
I am still not able to get it (maybe i am missing something ). If the government ( the majority shareholder ) controls the pricing (and profit) of the oil companies at the expense of the minority shareholder with no concern other than the political impact, what is the value of these companies ? how does one value such companies where the future cash flow in addition to being dependent on a volatile oil market is also dependent on a whimsical majority shareholder which has a non economic agenda ! . This sector would start looking like indian railways if the oil prices remain high (which looks likely), that is chronically sick
typically oil companies make good profits through forward contracts, hedging etc during rising oil prices (more so if they are vertically integrated). But the indian oil companies are actually down when the overall market is up ( see chart )
To provide cushion for under-recoveries — Standalone refineries may be merged with oil marketing cos --- From hindu business line
Our Bureau
New Delhi , Aug. 17
THE Ministry of Petroleum & Natural Gas is weighing the option of merging pure refining companies with oil marketing companies (OMCs) to enable the latter to cushion the impact of high global crude oil prices on their bottomline.
Due to the freeze by the Government on raising retail prices despite the rise in raw material cost, the fuel retailing business is seen as becoming economically unviable, resulting in OMCs such as Indian Oil Corporation, Bharat Petroleum Corporation, Hindustan Petroleum Corporation and IBP suffering losses.
However, standalone refiners in Chennai, Kochi and Mangalore are making profits as they get the international price for the fuel they produce.
Asked whether the Petroleum Ministry was contemplating such a move, the Petroleum Secretary, Mr S.C. Tripathi, told Business Line that, "various options are being considered. In view of the high crude oil price scenario, some serious structural changes could be made in the downstream sector."
About the suggestion made by the Committee on Synergy in Energy to oil companies asking them to consolidate their businesses, the Secretary said, "we are keeping that also in view."
Explaining the rationale behind such a consideration, a Petroleum Ministry official said standalone refiners were currently earning huge margins, while the OMCs were taking a hit. The merger could help in sharing refining margins with OMCs. "But this is a long-term view and may take some time," he said.
Meanwhile, the bleeding OMCs have been seeking a revision in the prices of the four petroleum products - kerosene, LPG, petrol and diesel.
The companies have incurred a cash loss of Rs 1,516 crore in July. They have sought Rs 5.29 per litre increase in petrol and Rs 4.54 a litre hike in diesel prices. Indications are that the Government is unlikely to consider the price revision before the end of the current session of Parliament.
Also, negotiations were on with the Finance Ministry to consider an excise duty cut, senior officials said.
The Government may consider a hike between Rs 1 and 2 per litre each combined with excise duty reduction on petrol from 8 per cent plus Rs 13 a litre to 8 per cent plus Rs 12 a litre and that on diesel from 8 per cent plus Rs 3.25 a litre to 8 per cent plus Rs 2.25 per litre.
Tuesday, August 16, 2005
Hotel stocks - some number
Pulled out these number from the equityresearchindia website. Pretty depressing economics ....guess one can make money on one can catch the inflexion point when the economy is turning and the hotel industry is poised to do well ...
2005 2004 2003 2002 2001 2000 1999
A) Return on Equity (i x ii) 9.20% 4.40% 3.20% 4.40% 8.90% 9.50% 11.90%
i) Return on Total Assets
4.70% 2.10% 1.60% 2.40% 5.20% 5.90% 7.90%
ii) Total Assets To Total Equity
2 2.1 2 1.8 1.7 1.6 1.5
B) Return on Total Assets (iii x iv) 4.70% 2.10% 1.60% 2.40% 5.20% 5.90% 7.90%
iii) Net Profit Margin
11.10% 6.60% 5.60% 8.20% 13.90% 15.40% 17.20%
iv) Total Assets Turnover
0.4 0.3 0.3 0.3 0.4 0.4 0.5
C) Total Assets Turnover (v / vi) 0.4 0.3 0.3 0.3 0.4 0.4 0.5
v) Total Income (Rs. Cr.)
3103 2452 2052 1924 2241 2012 2078
vi) Average Total Assets (Rs. Cr.)
7374 7597 7023 6577 5959 5260 4495
Hotel stocks
Was looking at the latest results of the hotel industry. The headlines are screaming about the triple digit growths and the tight demand supply situation. The rise in tourist inflows / good business climate are being cited as the reason for the optimism.
I am not too excited by the results or by the economics of the hotel industry. It is typical commodity industry. Some companies have good brand names, but do they have a strong franchise. What i mean by that is, can these companies charge a premium price? . Taj and others can charge a premium compared to the other hotels, but when there is excess supply, the typical occupancy rates and ARR (average room rents) suffer. During such period the margins drop and due to the high fixed costs , even the best of the companies can barely remain in black.
So over a complete business cycle most of the companies in this sector can barely cover their cost of capital. The asset turnover ratios are very low and so to earn a return over their cost of capital, most of these hotels need to maintain a Net profit margin in excess of 10 % ( a tall task when times are bad).
On the contrary this industry looks almost like the steel, cement and the other commodity industry, where only a low cost producer like gujarat ambuja or Tata steel can be profitable over the long term. Can't think of any such hotel company ...
Compare this with the FMCG/Pharma/IT and most of these companies even during a downturn, earn over their cost of capital.
As a side note, ITC seems to be investing their cash flows from ciggarette business to hotels, Paper and FMCG which are businesses with poor economics. Granted , that the company is getting growth, but is it profitable ( doesnt seem to be as of now)?
Monday, August 15, 2005
Added two blogs
I have added two blogs which i frequently read . One is mark cuban's blog and the other Victor Niederhoffer
Mark's biography is below
http://www.nba.com/mavericks/news/cuban_bio000329.html
and victor's is below
http://www.dailyspeculations.com/aboutus.htm
Both write excellent and thought provoking blogs
Mark's biography is below
http://www.nba.com/mavericks/news/cuban_bio000329.html
and victor's is below
http://www.dailyspeculations.com/aboutus.htm
Both write excellent and thought provoking blogs
Competition
Found this posting Victor Niederhoffer's blog on competition. I agree competition is good for society / consumer , but bad for an investor. I would prefer a company which is close to a unregulated monopoly ( a toll bridge as buffett says )
Competition, by Victor Niederhoffer:
Competition in its many aspects -- markets, trees, companies, old heartedness, protection of consumers, romance -- is the main force responsible for our high standard of living. It brings out the best in us and provides the consumer with the price and quality he wants. James Lorie, along with Franklin Fisher, was one of the chief consultants for IBM in the antitrust action against it in the 1970s. I came across this quote by Fisher vis a vis the similarities to the Microsoft case:
Every practice that the government complained of had to due basically with the offering of better products or lower prices. The government did not understand that that is the way competition works.
He then goes on to show how IBM had developed a better and smaller disk and the government complained it was a predatory device.
If only the public were educated to realize that there is always someone waiting around to provide a product at a more attractive price or quality or time or convenience, then so much wasted envy and loss would be averted.
A new world economy
A new article on india and china. interesting to read
http://www.businessweek.com/magazine/content/05_34/b3948401.htm
some excerpts
Even more exhilarating is the pace of innovation, as tech hubs like Bangalore spawn companies producing their own chip designs, software, and pharmaceuticals. "I find Bangalore to be one of the most exciting places in the world," says Dan Scheinman, Cisco Systems Inc.'s senior vice-president for corporate development. "It is Silicon Valley in 1999." Beyond Bangalore, Indian companies are showing a flair for producing high-quality goods and services at ridiculously low prices, from $50 air flights and crystal-clear 2 cents-a-minute cell-phone service to $2,200 cars and cardiac operations by top surgeons at a fraction of U.S. costs. Some analysts see the beginnings of hypercompetitive multinationals. "Once they learn to sell at Indian prices with world quality, they can compete anywhere," predicts University of Michigan management guru C.K. Prahalad. Adds A. T. Kearney high-tech consultant John Ciacchella: "I don't think U.S. companies realize India is building next-generation service companies."
Barring cataclysm, within three decades India should have vaulted over Germany as the world's third-biggest economy. By mid-century, China should have overtaken the U.S. as No. 1. By then, China and India could account for half of global output. Indeed, the troika of China, India, and the U.S. -- the only industrialized nation with significant population growth -- by most projections will dwarf every other economy.
China also is hugely wasteful. Its 9.5% growth rate in 2004 is less impressive when you consider that $850 billion -- half of GDP -- was plowed into already-glutted sectors like crude steel, vehicles, and office buildings. Its factories burn fuel five times less efficiently than in the West, and more than 20% of bank loans are bad. Two-thirds of China's 13,000 listed companies don't earn back their true cost of capital, estimates Beijing National Accounting Institute President Chen Xiaoyue. "We build the roads and industrial parks, but we sacrifice a lot," Chen says.India, by contrast, has had to develop with scarcity. It gets scant foreign investment, and has no room to waste fuel and materials like China. India also has Western legal institutions, a modern stock market, and private banks and corporations. As a result, it is far more capital-efficient. A BusinessWeek analysis of Standard & Poor's (MHP ) Compustat data on 346 top listed companies in both nations shows Indian corporations have achieved higher returns on equity and invested capital in the past five years in industries from autos to food products. The average Indian company posted a 16.7% return on capital in 2004, vs. 12.8% in China.
The burning question is whether India can replicate China's mass manufacturing achievement. India's info-tech services industry, successful as it is, employs fewer than 1 million people. But 200 million Indians subsist on $1 a day or less. Export manufacturing is one of India's best hopes of generating millions of new jobs.India has sophisticated manufacturing knowhow. Tata Steel is among the world's most-efficient producers. The country boasts several top precision auto parts companies, such as Bharat Forge Ltd. The world's biggest supplier of chassis parts to major auto makers, it employs 1,200 engineers at its heavily automated Pune plant. India's forte is small-batch production of high-value goods requiring lots of engineering, such as power generators for Cummins Inc. (CMI ) and core components for General Electric Co. (GE ) CAT scanners.
Measuring the moat - framework for evaluating competitive advantage
found this article on Michael Mauboussin's website. Absolutely fantastic article. Extremely helpful in developing a framework for evaluating a companies competitive advantage.
http://www.capatcolumbia.com/Articles/measuringthemoat.pdf
In addition , micheal has published this new article on the legg mason website. A must read !!
http://www.leggmason.com/funds/knowledge/mauboussin/Aver_and_Aversion.pdf
http://www.capatcolumbia.com/Articles/measuringthemoat.pdf
In addition , micheal has published this new article on the legg mason website. A must read !!
http://www.leggmason.com/funds/knowledge/mauboussin/Aver_and_Aversion.pdf
Friday, August 12, 2005
Analysing the auto component industry
I have been studying the Indian auto component industry for the last few days. The industry appears to have a good future ahead (whether there are some good stocks at good valuation is something i need to check).
The auto industry has two main channel - OEM and After sales. The industry has been restricted mainly to the domestic industry in the past and was thus tied to the fortune of the domestic auto industry (which in turn is cyclical).
A few changes have happened which have opened up the export market to this industry
- Recognition of India for its technical manpower. This is crucial especially in auto which involves a lot of R&D and design for new components at the higher end of the value chain
- Low cost labor
- Opening up of the Auto sector by the Indian government, due to which the global majors such as ford, GM etc setup shop in India and started sourcing from local suppliers. This helped in improving the competitiveness of the Indian auto component makers
- increase in scale of the domestic auto component makers and foray into the export market
Industry landscape
Some of the key firms in the industry in terms of their size are
- Bharat forge
- MICO
- Motherson Sumi
- Exide
- Sundaram fastners
Porter’s 5 factor analysis
Barriers to entry
- Technology: several auto components have a high technology component and can be produced by only those companies which have access to the technology or have developed it themselves. As a result most of the auto makers specialize in specific components
- Economies of scale
- Brand is crucial, more so in the Spares market (and as a result a distribution network too)
- Customer relationship in the form of long term contracts
Rivalry among firms
Rivalry among firms would be high in Spares market, but lesser in the export markets wherein the norm is long term contract. In addition the industry has high technology component and hence the industry does not deal in completely commodity product. However competition could be from other firms from other countries in a similar product line
Supplier power should be low as the key raw material is steel which in itself is a commodity
Buyer power is high especially for the OEM market and with high competition between auto makers there should be a constant pricing pressure on the auto component makers going forward
I would consider the threat of substitute product as low
The key success factors for the industry going forward should
- Continued investment into technology/ process to build barriers to competition and provide a cost and quality advantage to the customer
- Pursuit of economies of scale to be cost competitive. It should be in both production and in R&D
- Developing strong customer relationship through quality and reliable supply
Key risks
- Pricing would remain under pressure going forward
- Inability to meet the supply schedules of the customer
- Development of alternative outsourcing locations
The industry is into a growth phase. However the market also seems to have recognized that and most of the companies seem to be fairly valued.
Thursday, August 04, 2005
Black Swan effect – Fat outliers / Why EMT varies from reality
EMT – Efficient market hypothesis has been debated to death. There are people who swear by it, atleast in the weak form.
One area where EMT differs from reality is in its modeling of outliers, rare events or black swan (This is the term used by Nicholas M Taleb).
To get a better understand of this topic, I have been reading the book – Fooled by randomness – by Nicholas M Taleb. He uses a lot of real life examples to explain some very complex concepts.
Some ideas which have remained with me are
- Black swan or Rare events or Outlier events happen more frequently than one would think so (drawback of the EMT ? )
- The EMT models the market by normal distribution, which does not take account of these outlier events. Hence you find these spectacular hedge fund blow up like LTCM where a rare event takes the fund down
- People under estimate chance in life and attribute it to skill (in investing too)
- Human mind is not designed to be rational, especially in the area of finance and we tend to make emotional suboptimal decision
- The pain of loss is 2-2.5 times more than the pleasure of gain. As a result, if one has the tendency to check his portfolio too often, it could have a negative impact on the performance ( if one were to act irrationally based on the short term performance )
- Most of the studies on long term performance of stocks / mutual funds have a survivorship bias due to which the performance appears better than it actually is (for ex: the current sensex does not have all those companies which were a part of it and went bankrupt or got knocked off)
A good book and a must read !!
Wednesday, August 03, 2005
No one Looks good !! - lesson for investors
A fantastic post on the Fool's BRK board from elias fardo. Its a must read for a value investor
http://www.fool.com/community/pod/2005/050802.htm?ref=foolwatch
If one were to follow these principles, he could the harshad mehta bust, the MS shoes debacles, the fraudulent IPO's of the past and a host of other scams.
http://www.fool.com/community/pod/2005/050802.htm?ref=foolwatch
If one were to follow these principles, he could the harshad mehta bust, the MS shoes debacles, the fraudulent IPO's of the past and a host of other scams.
Tuesday, August 02, 2005
Distinguishing between a commodity business and franchise
One of the analysis i have been doing for some time is to analyse various industries like cement, steel, media, gas , FMCG etc and try to asess their competitive scenario. The reason for doing this analysis is to gain a better understanding of these industries, compare them with each other and also to develop some kind of models / categorisations.
One of the frustations i have felt , is the lack of litreature on the various types of business models. The typical one that get discussed are the ideal franchise like business models like coke ( at global level ) or nestle, asian paints, HLL etc at an indian level. The other extreme are the absolute commodity type businesses like airlines, steel ( i agree that within these commodity type business there are some value creating companies).
But there are businesses out there, which lie between the two extremes. For example auto components, power , banks, branded textiles etc. I am trying to analyse these various industries on porter's five factor model and other variables so that i can conceptually think about a business and assign it to a model (not the best approach, but makes it easier to analyse a company and gives a starting point
While i was doing this, yesterday, i came across one such exercise being done ( http://pink-sheets.blogspot.com/ <http://pink-sheets.blogspot.com/> ). Should be helpful to me in my exercise
Friday, July 29, 2005
Buffett's comment on telecom industry
The other day i posted a link for a talk which buffett gave in omaha. One of the question was on his opinion of the telecom industry. He said that he cannot predict the future of industry ( said he does not even know the complete history) and the industry has too much change (which is bad for the investor)
This had me thinking and then i came across this article below in economist (link given , i have added on a portion of the article as it could have some copyright issues ). On reading this article, i think one would tend to agree with buffett. It is very difficult to really predict the long term business model of the telecom industry. Today VOIP is the killer app , tomorrow it could be something else ....
http://www.economist.com/business/displayStory.cfm?story_id=4232442
Established telecoms companies are fighting an increasingly bitter battle against innovative attackers
That is because IPTV forms part of a larger, and quite desperate, defensive strategy now being adopted by telecoms firms against fierce attacks on multiple fronts. On one front are cable giants, such as America's Comcast, which are luring customers with an enticing “triple-play bundle” of TV, broadband and telephony services. On a second front are mobile-phone operators, which young customers in particular are increasingly using to “cut the cord” from their fixed-line company.
But arguably most dangerous of all is the third front, where traditional telecoms firms are under attack from voice-over-internet-protocol (VOIP) providers, which use the internet to carry conversations that would previously have taken place via a conventional phone. TeleGeography, a research firm, estimates that the number of subscribers to VOIP services such as Vonage, which lets users plug their traditional phones into a gadget connected to the internet, will grow from 1.8m at the start of this year to 4m by the end of December in America alone; by 2010, it projects over 17m American subscribers. This does not count the world's largest VOIP provider, Skype, which uses a small and simple software application to let users make free calls between computers—so far, it has been downloaded 141m times.
Hanging on the telephone
Traditional telecoms firms are doing their best to respond to these threats by adopting internet technologies themselves. This week, VSNL, the top operator in India for international calls, said it would buy Teleglobe, the world's largest international wholesale VOIP carrier. Every big telecoms firm is investing to migrate from old, circuit-switched networks to new internet-based ones, with Britain's BT probably moving fastest. The threat from VOIP would then be neutralised, as the telecoms firms themselves would be providing it. Even so, VOIP makes already grim revenue forecasts for old-style telecoms firms look truly depressing (see chart).
Tuesday, July 26, 2005
Checking on pidilite results
Just saw pidilite industries results yesterday. The topline growth in consumer goods is still very strong ( 15% +). The industrial division continues to do well too. The bottomline was under pressure which i expected with the oil prices being high and one of the key raw materials being VAM which is dependent on crude prices.
Pidilite continue to do well, increasing market shares in the key categories ( i need to figure, how the new products are doing ).
The only worry which i have had with pidilite, which has prevented me from expanding on my holding, is what would the management do with all the free cash flows. The past record has been patchy. They have invested in windmills !! loaned to subsidiary companies and so on. somehow i have not been to been able to be comfortable on this factor.
But fundamentally the business continues to perform well
cannot upload files
i have been trying to figure a way to upload files on warren buffett's visit to various colleges, articles on ben graham etc. unfortunately have not been able to find any way to do so ...if any one has an idea can you please leave a comment
thanks !
thanks !
cannot upload files
i have been trying to figure a way to upload files on warren buffett's visit to various colleges, articles on ben graham etc. unfortunately have not been able to find any way to do so ...if any one has an idea can you please leave a comment
thanks !
thanks !
Subscribe to:
Posts (Atom)